Key Takeaways
- The Empire Plan under NYSHIP describes its out-of-area benefits as available worldwide, so treatment at qualified facilities outside New York is generally covered 5.
- Covered does not mean free — network status, prior authorization, and Medicare coordination all shift what a family actually pays for the same clinical stay 10.
- Non-emergency care, including planned residential psychiatric or dual diagnosis admissions in another state, sits inside the benefit structure rather than being an exception 9.
- Verifying a specific program takes three steps: identify the exact NYSHIP plan, confirm the facility’s network status, and request a formal benefits verification before admission 3, 12.
The Short Answer for Families Looking Beyond New York
Yes. If you or your family member has The Empire Plan through NYSHIP, your coverage generally follows you across state lines. NYSHIP’s own 2026 plan materials say out-of-area benefits for covered services are available worldwide 5. That includes specialized psychiatric and substance use treatment at facilities outside New York.
Here’s the part that trips people up: covered is not the same as free. Your plan may pay a different share depending on whether the facility is in-network, whether prior authorization is needed, and whether you’re a retiree with Medicare in the mix 10. Those details change what you actually owe, even when the treatment itself is a covered service.
You’re likely reading this because standard local care hasn’t worked and you’re looking further afield. That’s a hard place to be, and calling an insurance line to decode a benefits booklet is the last thing you have energy for. The good news: you don’t have to do it alone. ViewPoint’s admissions team can verify your specific NYSHIP benefits directly, so you get a clear answer about a specific program without spending your afternoon on hold.
What NYSHIP Actually Says About Care Outside New York
The Empire Plan Travels With You
If you have The Empire Plan, geography is not the barrier you might think it is. NYSHIP’s own 2026 Plan Comparison puts it plainly: out-of-area benefits for covered services are available worldwide 5. Not just neighboring states. Not just the East Coast. Worldwide.
That same worldwide language shows up in the 2026 active choices document and the NYSHIP Plan Comparison Tool, which also confirms you may choose The Empire Plan regardless of where you live or work 6, 8. The rates and deadlines publication lists The Empire Plan as available to enrollees and their covered dependents worldwide, too 7. So this is not a one-line promise buried in a footnote — it is the consistent position across NYSHIP’s current materials.
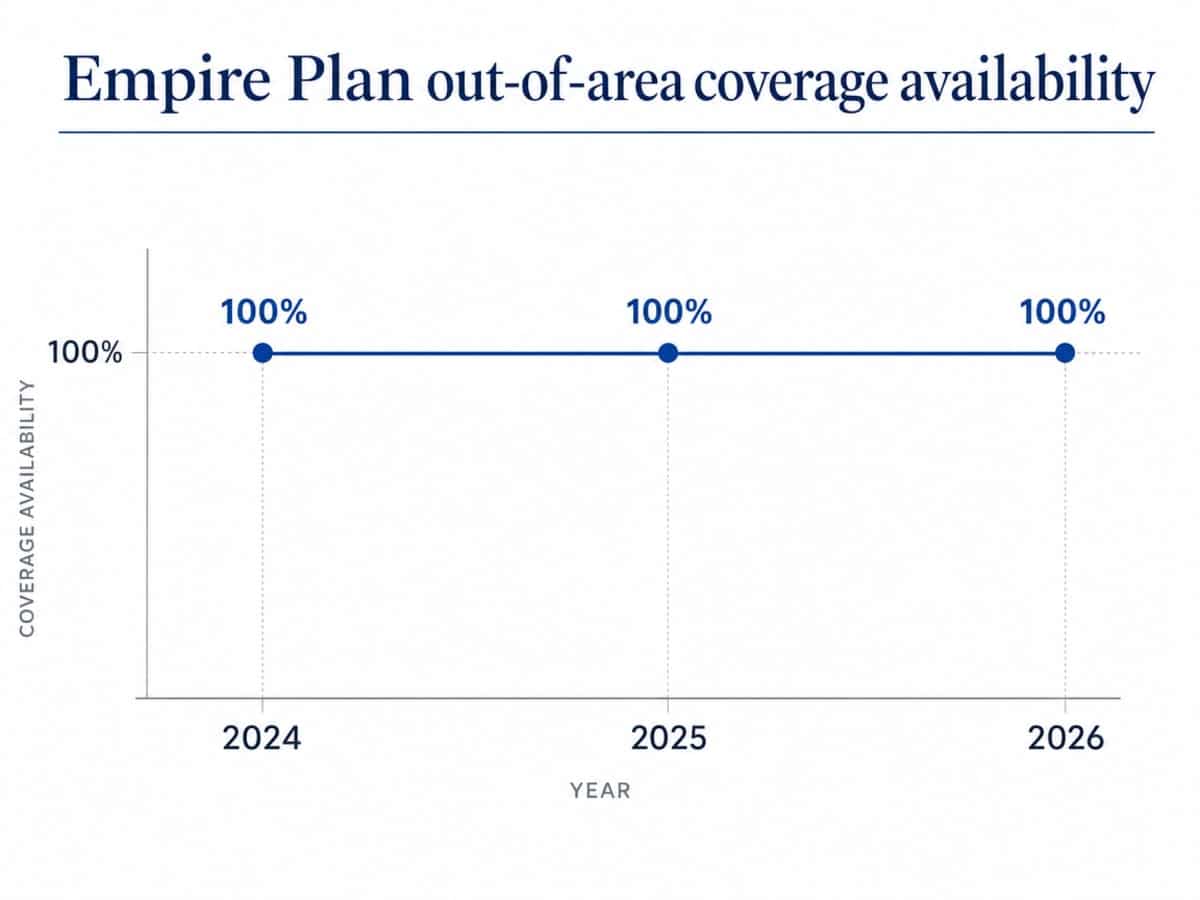
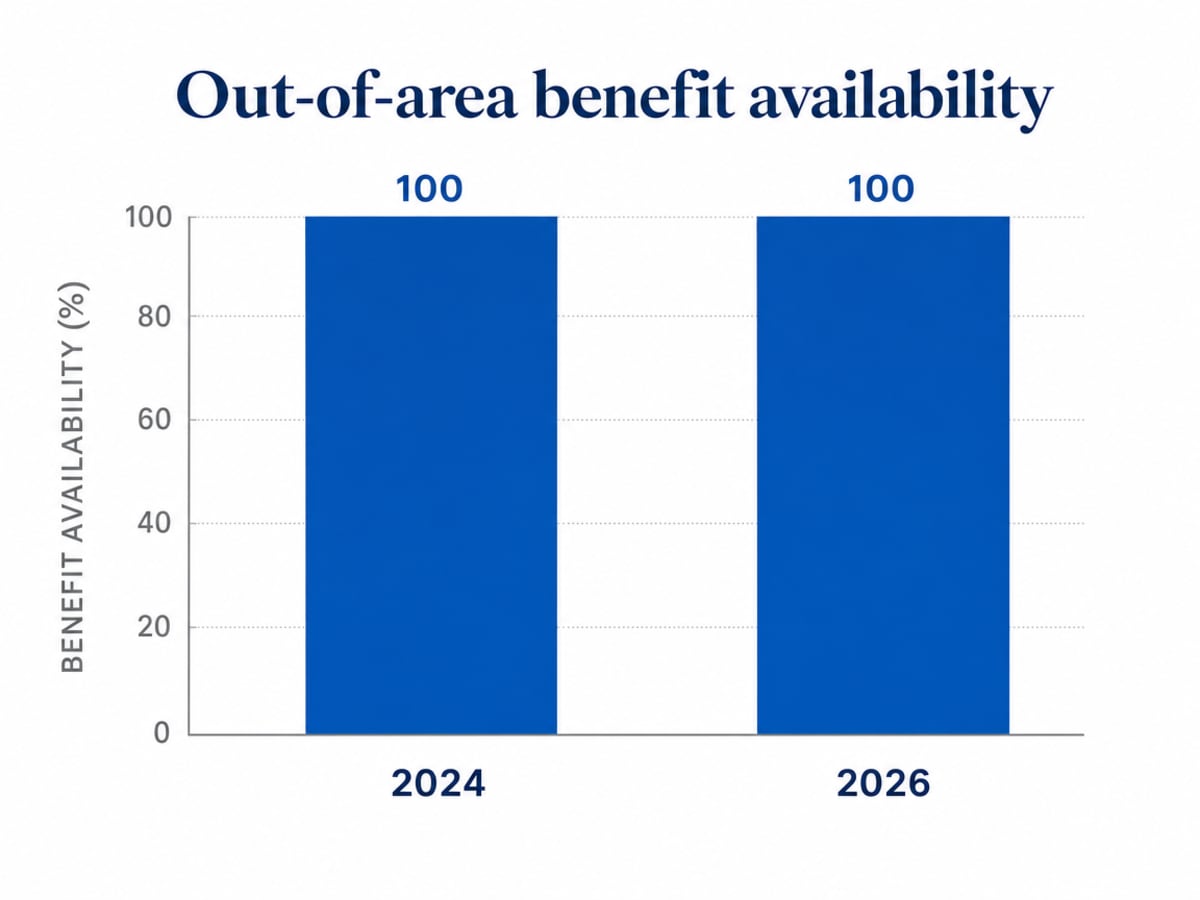
The contrast matters. Empire Plan out-of-area benefit availability has held steady at essentially 100% worldwide across recent plan years, while most NYSHIP HMO options are tied to a defined service area inside or near New York 5, 6. If your loved one enrolled in an HMO because it was the cheaper option at open enrollment, sending them to a specialty program in Arizona is a very different conversation than it is for an Empire Plan member.
The practical takeaway: knowing which NYSHIP plan you actually have is step one. Pull out the ID card or log in to your NYSHIP account before you do anything else. That single detail changes almost every answer that follows.
If You Live Outside New York, Your Plan Choice Is Narrower
Here is a wrinkle that catches families off guard. Maybe you retired to Florida. Maybe your adult child took a job that let them work remotely from Colorado. Maybe you moved to be closer to grandchildren. When residency changes, your NYSHIP options change with it.
NYSHIP’s official enrollment guidance is direct: if you reside outside New York State, your only NYSHIP option is The Empire Plan 2. The HMO menu that active employees in Albany or Buffalo can pick from is not available to you. That sounds limiting, but for the specific question you’re researching, it is actually good news. The Empire Plan is the option with worldwide coverage in the first place 5.
So if you or your adult child lives out of state and you’ve been worried that a move disqualified the family from meaningful coverage for out-of-state care, take a breath. It usually does the opposite. You end up on the NYSHIP plan best suited to travel across state lines.
A quick honesty check: this rule applies to where the covered person resides, not just where the treatment happens. If your college-age dependent lives in another state during the school year, that matters for their enrollment path. If you are the enrollee and you split time between New York and another state, your permanent address is what NYSHIP looks at. When in doubt, confirm your residency of record with your health benefits administrator before you assume.
Non-Emergency Care Is Inside the Benefit, Not an Exception
People sometimes assume out-of-state coverage only kicks in for emergencies — a broken leg on vacation, a heart attack at a conference. That assumption can talk families out of options they actually have.
The Empire Plan’s Summary of Benefits and Coverage explicitly lists non-emergency care when traveling outside the U.S. as part of the benefit structure 9. If planned care abroad is inside the plan, planned care in another U.S. state is well within it. Nothing in NYSHIP’s worldwide-coverage language limits it to emergencies 5, 12.
That distinction is the one that opens the door to specialty psychiatric care outside New York. Residential treatment for a treatment-resistant condition. A structured dual diagnosis program. Advanced medication management like clozapine protocols that not every local hospital runs. These are planned, non-emergency admissions. And the framework to cover them is already sitting inside your plan documents 9.
You still need to confirm the specifics for a specific facility and level of care. Worldwide coverage does not mean identical cost-sharing everywhere, which is the next thing to sort out. But the door is open. You are not asking for an exception.
Covered Is Not the Same as Free: Where Costs Actually Change
Network Status of the Facility
This is where most families get their first real surprise. A service being covered by The Empire Plan and a facility being in-network with The Empire Plan are two different things, and the gap between them shows up on the bill.
When a psychiatric or dual diagnosis program is in-network, the plan pays its share directly, and your out-of-pocket costs are the standard cost-share numbers on your ID card. When the program is nonparticipating, the same treatment is often still covered, but the plan pays at a different rate and the facility can bill you for the balance. NYSHIP’s own Out-of-Network Reimbursement Disclosures spell this out and direct members to call 1-877-7-NYSHIP with coverage questions before assuming anything 10.
The mechanics can also change how you pay. For non-network hospital care, the 2025 Empire Plan Worldwide guidance notes that members are entitled to network-level benefits but may have to pay upfront and submit a claim for reimbursement afterward 1. That is a very different cash-flow situation than handing over an ID card at admission.
Level of Care and Prior Authorization
The other place costs shift is the level of care itself. A single outpatient therapy session and a 30-day residential admission are both mental health treatment, but they travel through your plan very differently.
Higher levels of care — inpatient psychiatric hospitalization, residential treatment, partial hospitalization, intensive outpatient — typically require prior authorization from The Empire Plan before admission. That is not NYSHIP being difficult. It is the standard way the plan confirms the care is medically necessary and agrees to pay its share. Skipping the authorization step can turn a fully covered stay into a denied claim, even when the underlying benefit exists 10.
For a treatment-resistant psychiatric case, that authorization conversation is where the clinical story matters most. The plan needs to see why standard outpatient care has not worked, why a higher level of care is appropriate now, and why the specific program fits the diagnosis. A program that specializes in complex cases usually knows how to document this well. A general facility may not.
Retiree travel guidance and the NYSHIP FAQ both instruct members to call The Empire Plan at 1-877-7-NYSHIP before seeking non-emergency services, precisely because these authorization steps sit between coverage on paper and coverage in practice 3, 12. Making that call — or having someone make it for you — is not a hoop. It is how you protect the family from a bill nobody expected.
What You Pay Up Front vs. What Gets Reimbursed
Even after coverage and authorization are settled, there is one more question worth asking early: how does the money actually move?
With an in-network facility, most costs flow directly between the provider and The Empire Plan. You handle your cost-share, and the rest is invoiced behind the scenes. With a nonparticipating provider — especially for hospital-level care — you may be asked to pay for services and then submit a claim for reimbursement at network-level benefits 1. For out-of-country care, NYSHIP’s 2025 General Information Book gives the same instruction: file claims directly with The Empire Plan 4.
That reimbursement model is not a dealbreaker, but it does change your planning. You want to know before admission whether the family will need to front any portion of the stay, what the claim process looks like, and how long reimbursement typically takes. Those answers are specific to the facility and to your plan year.
This is exactly the kind of detail that is hard to nail down from a benefits booklet at 10 p.m. after a rough day. It is not hard for the people who read these documents for a living. Handing the question to an admissions team that verifies NYSHIP benefits regularly is often the fastest way from worry to a real number.
The Medicare-Eligible Retiree Case
A quick audience shift: this section is for NYSHIP retirees who also have Medicare, or the adult children helping them sort through options. If that’s not you, you can skim.
When a NYSHIP retiree becomes Medicare-eligible, Medicare typically becomes primary for most care inside the United States, and NYSHIP wraps around it as secondary. For out-of-state psychiatric or dual diagnosis treatment at a domestic facility like one in Arizona, that coordination is the norm. Medicare pays first at the facility, and The Empire Plan picks up what Medicare doesn’t, subject to the plan’s rules on network status and prior authorization 10.
The mechanics change if the treatment is outside the United States. Medicare generally does not pay for care outside the U.S., with only narrow exceptions 13. NYSHIP has a specific policy memo for this situation: if a NYSHIP enrollee incurs medical expenses outside the United States, NYSHIP pays as primary insurer whether or not the person is enrolled in Medicare 11. The 2025 General Information Book adds that if your permanent residence is outside the U.S., enrollment in Medicare is not required by NYSHIP 4.
For your situation — a domestic out-of-state program — the practical takeaway is short. Bring both your Medicare card and your Empire Plan card to admissions. Ask specifically how the facility bills Medicare first and NYSHIP second, and whether prior authorization needs to go through Medicare, The Empire Plan, or both. That last question is where retiree admissions often stall, and it’s one an experienced admissions team can settle in a single call.
How to Verify Coverage for a Specific Out-of-State Program
Three Steps to a Real Answer
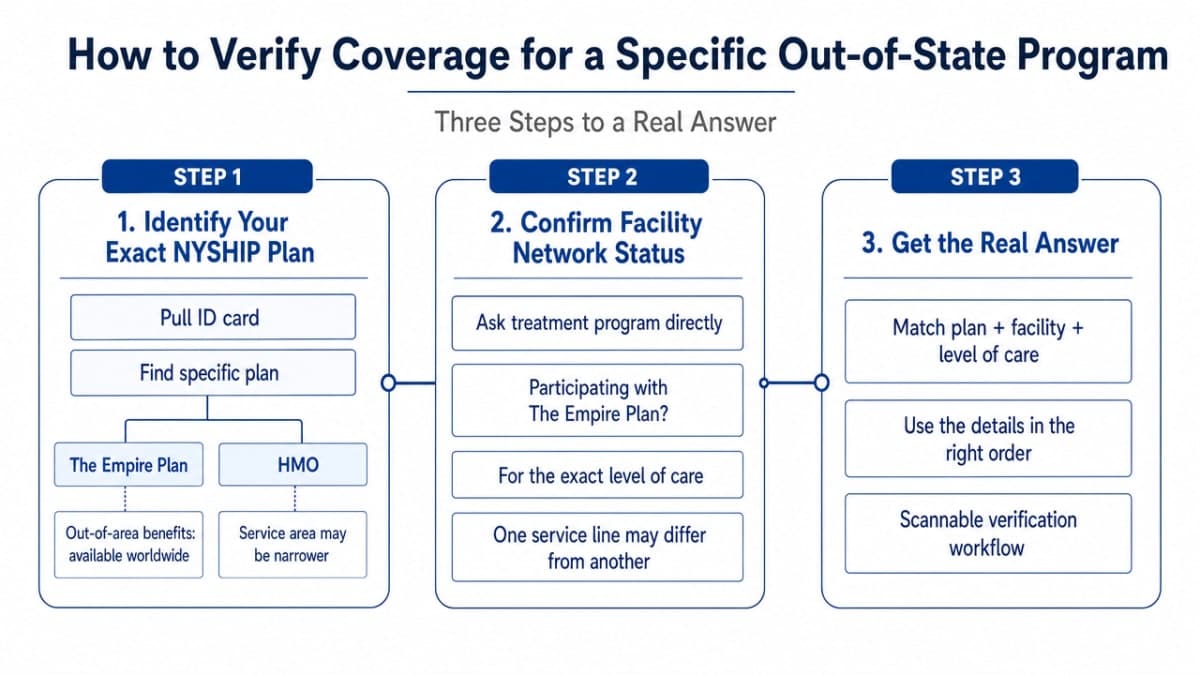
You don’t need a benefits degree to get a straight answer. You need three things in the right order, and each one is small enough to do in a single sitting.
- Step one: identify your exact NYSHIP plan. Not just “NYSHIP” — the specific plan. Pull the ID card. Look for The Empire Plan or the name of an HMO. If it’s The Empire Plan, you already know the plan’s out-of-area benefits are described as available worldwide in NYSHIP’s own 2026 materials 5. If it’s an HMO, the service area is likely narrower and the next steps change.
- Step two: confirm the facility’s network status. Ask the treatment program directly whether they are participating with The Empire Plan, and specifically for the level of care you’re considering. A facility can be in-network for one service line and not another. This is the single question that most changes what you’ll owe 10.
- Step three: request a formal benefits verification. This is the call that turns general coverage into real numbers for a real admission. NYSHIP’s retiree travel guidance and the NYSHIP FAQ both instruct members to call The Empire Plan at 1-877-7-NYSHIP before seeking non-emergency services, and both confirm that Empire Plan benefits are available worldwide 3, 12. That call gets you a case-specific answer on cost-share, prior authorization, and how claims will be paid.
Three steps. One afternoon, if that. Each step makes the next one shorter.
Questions to Ask on the Verification Call
If you’re the one making the call, keep a notebook next to you. Write down the date, the time, the name of the person you spoke with, and a reference number for the call. That paper trail matters if a claim is later processed differently than you were told.
Then ask these questions in this order. They build on each other.
- Is [facility name] participating with The Empire Plan for [level of care — for example, residential treatment, partial hospitalization, or inpatient psychiatric]?
- What is the member cost-share for that level of care at that facility for this plan year?
- Is prior authorization required before admission? Who submits it — the facility or the member?
- How are claims paid — directly to the facility, or do we pay up front and file for reimbursement 1?
- Does mental health and substance use treatment go through the same benefit manager as medical care, or a separate one?
- For a Medicare-eligible member: how does Medicare coordinate with The Empire Plan for this admission 10?
Letting the Admissions Team Make the Call for You
Here is the part that’s easy to miss when you’re stressed: you don’t have to do any of this yourself.
A specialty program’s admissions team verifies benefits every day. They know which questions to ask, which department at NYSHIP handles mental health authorizations, and how to document the clinical picture for a treatment-resistant case so the review goes smoothly. What might take you a week of phone tag often takes them a single call.
ViewPoint’s admissions team can verify your NYSHIP coverage directly. You share the member ID, the patient’s basic information, and a rough picture of what’s been tried already. They contact The Empire Plan, work through network status and authorization, and come back to you with a real answer for your family — usually within a business day.
You still make the decisions. You still get to say yes or no. But you don’t have to spend the evening reading a certificate of coverage after a hard day. That’s a reasonable thing to hand off, and handing it off is progress, not a shortcut.
Common Situations That Trip Up NYSHIP Members
A few scenarios come up again and again when families start researching out-of-state care. None of them are dealbreakers. All of them are worth knowing about before you’re on the phone with an admissions coordinator trying to hold everything in your head.
- You confused NYSHIP with The Empire Plan. NYSHIP is the umbrella. The Empire Plan is one option under it, and it’s the option with worldwide out-of-area benefits 5. If you’re actually enrolled in a NYSHIP HMO, the answer to “does it travel” is very different. Check the ID card before you assume.
- Your dependent lives in a different state than you do. A college student in another state, an adult child on your plan who moved for work — residency matters for enrollment options 2. It usually pushes families toward The Empire Plan, which is the better setup for out-of-state care anyway.
- You called, got “it’s covered,” and stopped there. Covered is a category, not a number. Without confirming network status, prior authorization, and the payment path, you don’t yet have an answer you can plan around 10.
- You assumed emergency-only coverage. Planned, non-emergency care sits inside the benefit for The Empire Plan, not outside it 9. A residential admission for a treatment-resistant case is not an exception you have to argue for.
If any of these describe where you are right now, that’s normal. Sorting them out is exactly the kind of work ViewPoint’s admissions team does on your behalf.
Confirm your out-of-state NYSHIP treatment options
Get a personalized answer on NYSHIP coverage for specialized care in Arizona.
Frequently Asked Questions
Does The Empire Plan cover treatment at facilities outside New York State?
Yes. The Empire Plan’s out-of-area benefits for covered services are described as available worldwide in NYSHIP’s 2026 Plan Comparison, which includes specialty psychiatric and substance use treatment at facilities in other states 5. What changes from one facility to another is your cost-share, not whether the underlying benefit exists. Network status and prior authorization are the details that determine what you actually pay 10.
What’s the difference between a facility being covered and being in-network?
Covered means the service falls inside your benefit. In-network means the facility has an agreement with The Empire Plan on how much it will charge. A nonparticipating provider can still deliver a covered service, but the plan pays at a different rate and the facility may bill you for the balance 10. For non-network hospital care, you may also need to pay up front and file for reimbursement 1.
Do I need prior authorization before starting out-of-state residential or psychiatric care?
For higher levels of care like residential treatment, inpatient psychiatric, or partial hospitalization, yes, prior authorization is typically required before admission. Skipping that step can turn a covered stay into a denied claim 10. NYSHIP’s own guidance tells members to call The Empire Plan at 1-877-7-NYSHIP before seeking non-emergency services 3, 12. A specialty admissions team can handle that authorization conversation for you.
If I moved out of New York, can I still keep my NYSHIP coverage?
Yes, but your plan choice narrows. If you reside outside New York State, your only NYSHIP option is The Empire Plan 2. For out-of-state treatment, that is actually the plan you want, because its out-of-area benefits are described as available worldwide and it’s available regardless of where you live or work 5, 8. Confirm your residency of record with your health benefits administrator if you’ve recently moved.
How does coverage work if I’m a NYSHIP retiree who also has Medicare?
For domestic out-of-state care, Medicare is typically primary and The Empire Plan wraps around it, subject to network status and authorization rules 10. Bring both cards to admissions and ask how each plan is billed. Outside the U.S. the rules flip: Medicare generally does not pay for care abroad 13, and NYSHIP pays as primary insurer for medical expenses incurred outside the United States 11.
How do I verify what my specific plan will pay at a specific out-of-state program?
You have two paths. You can call The Empire Plan at 1-877-7-NYSHIP yourself and ask about network status, cost-share, prior authorization, and how claims are paid for that specific facility and level of care 3, 12. Or you can share your NYSHIP member ID with ViewPoint’s admissions team and let them make the call on your behalf. Either way, get a case-specific answer before admission — not just “it’s covered.”
References
- The Empire Plan Worldwide (2025) – NYS Civil Service. https://www.cs.ny.gov/employee-benefits/shared/publications/ep-travel-guides/2025/ep-ww-2025.pdf
- Paying for Coverage – CS.NY.gov. https://www.cs.ny.gov/employee-benefits/nyship/shared/option-transfer/guide/paying-for-coverage.cfm
- ON THE ROAD – CS.NY.gov. https://www.cs.ny.gov/employee-benefits/hba/shared/publications/on-the-road/2023/ny-ret-on-the-road-2023.pdf
- 2025 General Information Book – CS.NY.gov. https://www.cs.ny.gov/employee-benefits/nyship/shared/publications/general-information-book/2025/pe-gib-2025.pdf
- 2026 NYSHIP Plan Comparison – CS.NY.gov. https://www.cs.ny.gov/employee-benefits/nyship/shared/apps/plan-comparison/compare.cfm?plancode=001&group=6
- active-choices-2026.pdf – CS.NY.gov. https://www.cs.ny.gov/employee-benefits/shared/publications/choices/2026/active-choices-2026.pdf
- nyship – rates and deadlines – NYS Civil Service. https://www.cs.ny.gov/employee-benefits/shared/publications/rates/2026/ny-active-rates-2026.pdf
- NYSHIP Plan Comparison Tool – CS.NY.gov. https://www.cs.ny.gov/employee-benefits/nyship/shared/apps/plan-comparison/
- Summary of Benefits and Coverage: What this Plan Covers …. https://www.cs.ny.gov/employee-benefits/sbc/pdfs/2026/ny-unrep-sbc-2026.pdf
- Out-of-Network Reimbursement Disclosures – NYS Civil Service. https://www.cs.ny.gov/employee-benefits/shared/publications/out-of-network/2026/settled-oon-2026.pdf
- Medicare Reimbursement for Members Who Live Outside of the …. https://www.cs.ny.gov/employee-benefits/nyship/shared/apps/policymemos/viewMemo.cfm?memoid=126
- Frequently Asked Questions – Health Insurance for Local …. https://www.cs.ny.gov/employee-benefits/pa-market/faq.cfm
- Medicare Coverage Outside the United States. https://www.medicare.gov/publications/11037-medicare-coverage-outside-the-united-states.pdf